
Roof Insurance Claim in San Antonio
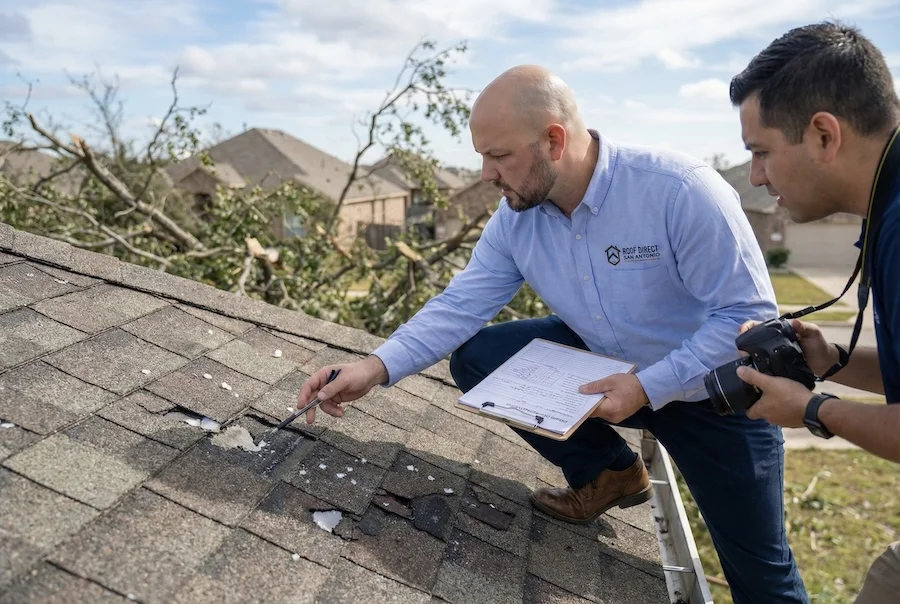
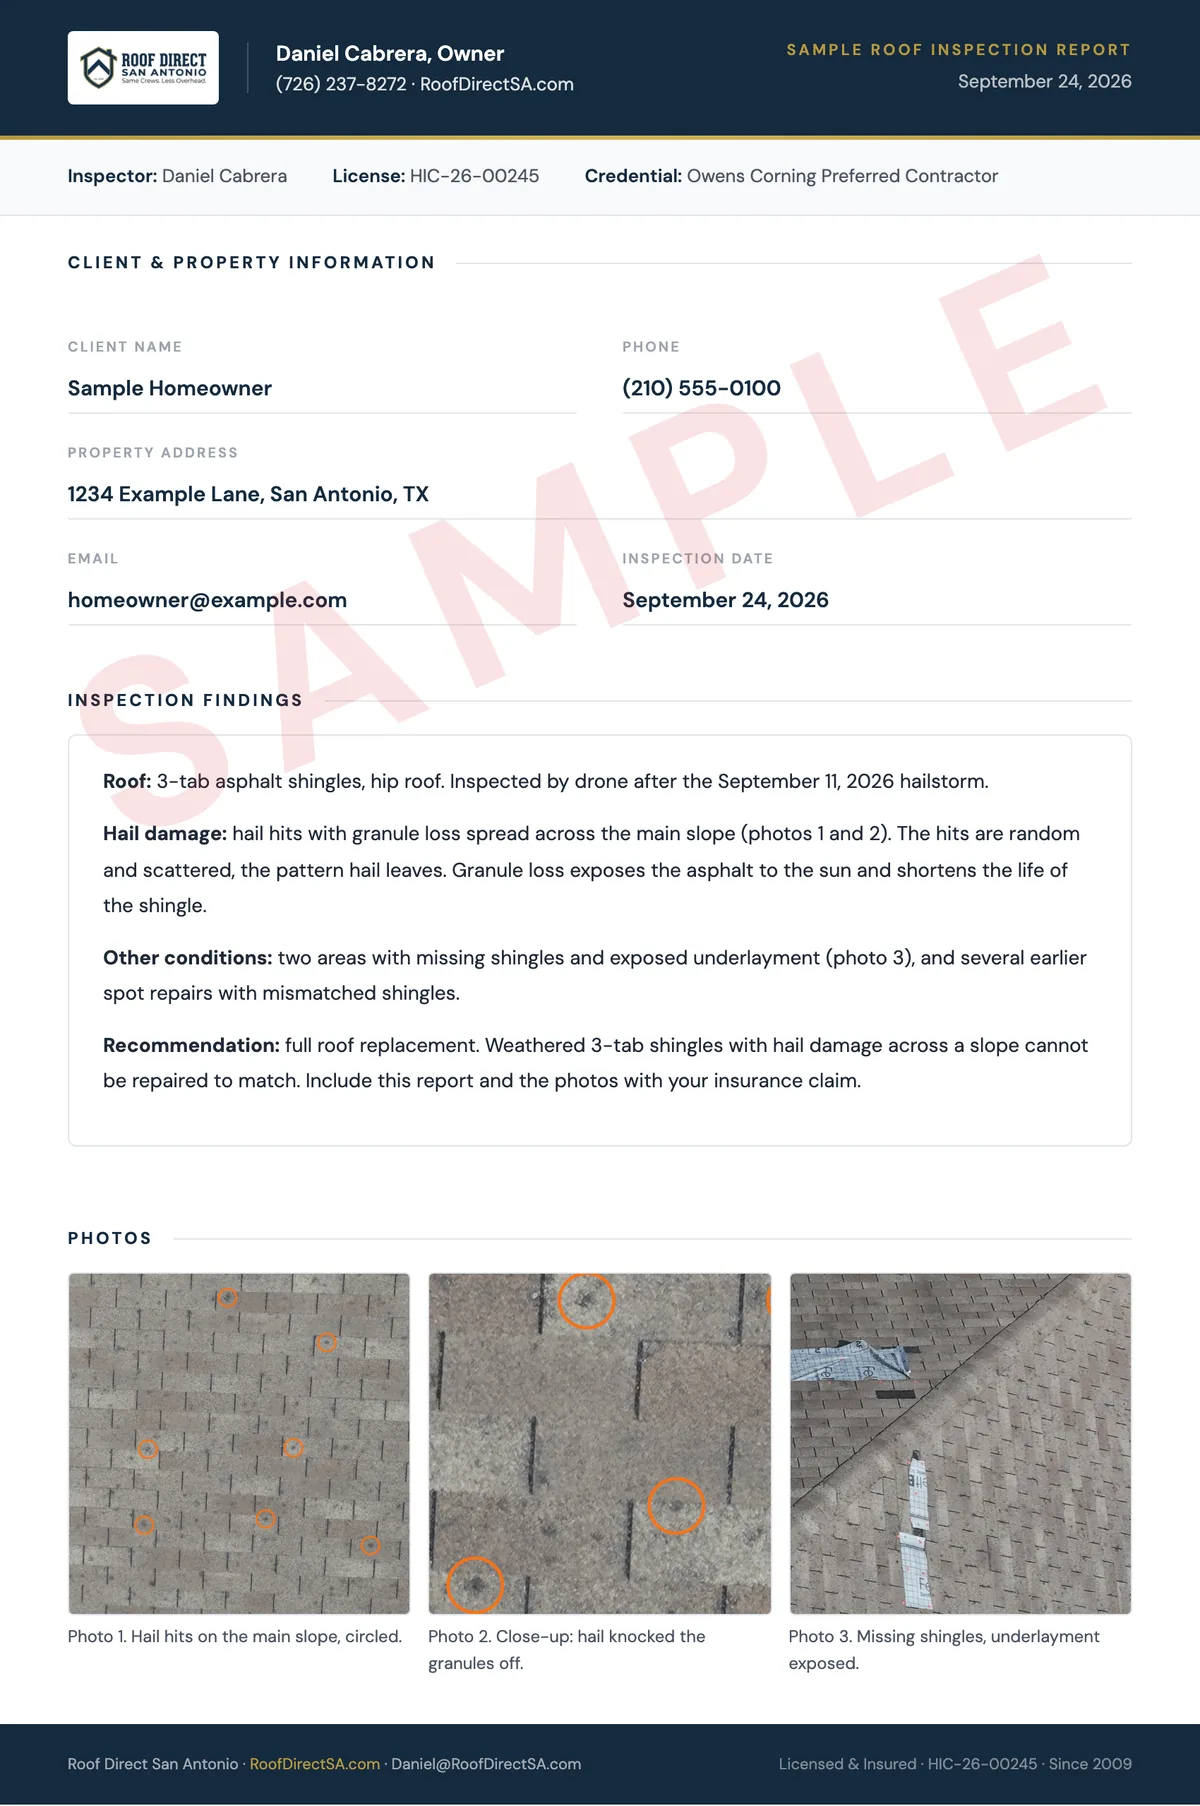
A roof insurance claim in San Antonio starts with proof of damage. We inspect your roof at no cost, give you a written report with photos, and are on site when your adjuster inspects. Claim already approved? On most claims the same payout covers a better shingle than the one you had, because there are no sales commissions in our price.
See Your Price in 2 Minutes. Free Damage Inspection Included.
Claim already approved? See what your payout covers with us
- ✓ Free inspection and written damage report
- ✓ On site when your adjuster inspects
- ✓ Deductible financing available
 OC Preferred


Insurance roof replacement in San Antonio: what we do
Insurance pays for the roof. These are the parts we handle, and the one part that stays with you.
- A better roof for the same payout. Your adjuster's estimate pays to replace the roof you had. There are no sales commissions or billboard budgets in our price, so on most claims that same amount covers Owens Corning Duration in place of 3-tab, and Class 4 impact-resistant shingles where it reaches. Class 3 and Class 4 shingles can both qualify for annual homeowner insurance premium discounts.
- Free inspection and written damage report. Photos of every slope, vent and flashing. The report is yours to send to your insurer.
- Documentation in your insurer's format. A detailed Xactimate-formatted scope for your claim.
- On site for the adjuster's inspection. We answer questions about the roof. You stay in control of your claim.
- Supplement paperwork. If the approved scope misses items, we prepare the supplement documentation for you to submit, at no extra cost.
- Your deductible. You pay it, whichever roofer you choose. Texas law requires it. Financing is available for the deductible.
Enter your address to see your replacement price in under 2 minutes. When you want the inspection, book the call and we schedule it there.
Insurer dropping you over the roof's age, not damage? That is a different path: roof too old for insurance. For the damage itself, see hail damage, storm damage or wind damage.
Claim approved? What your payout covers with us
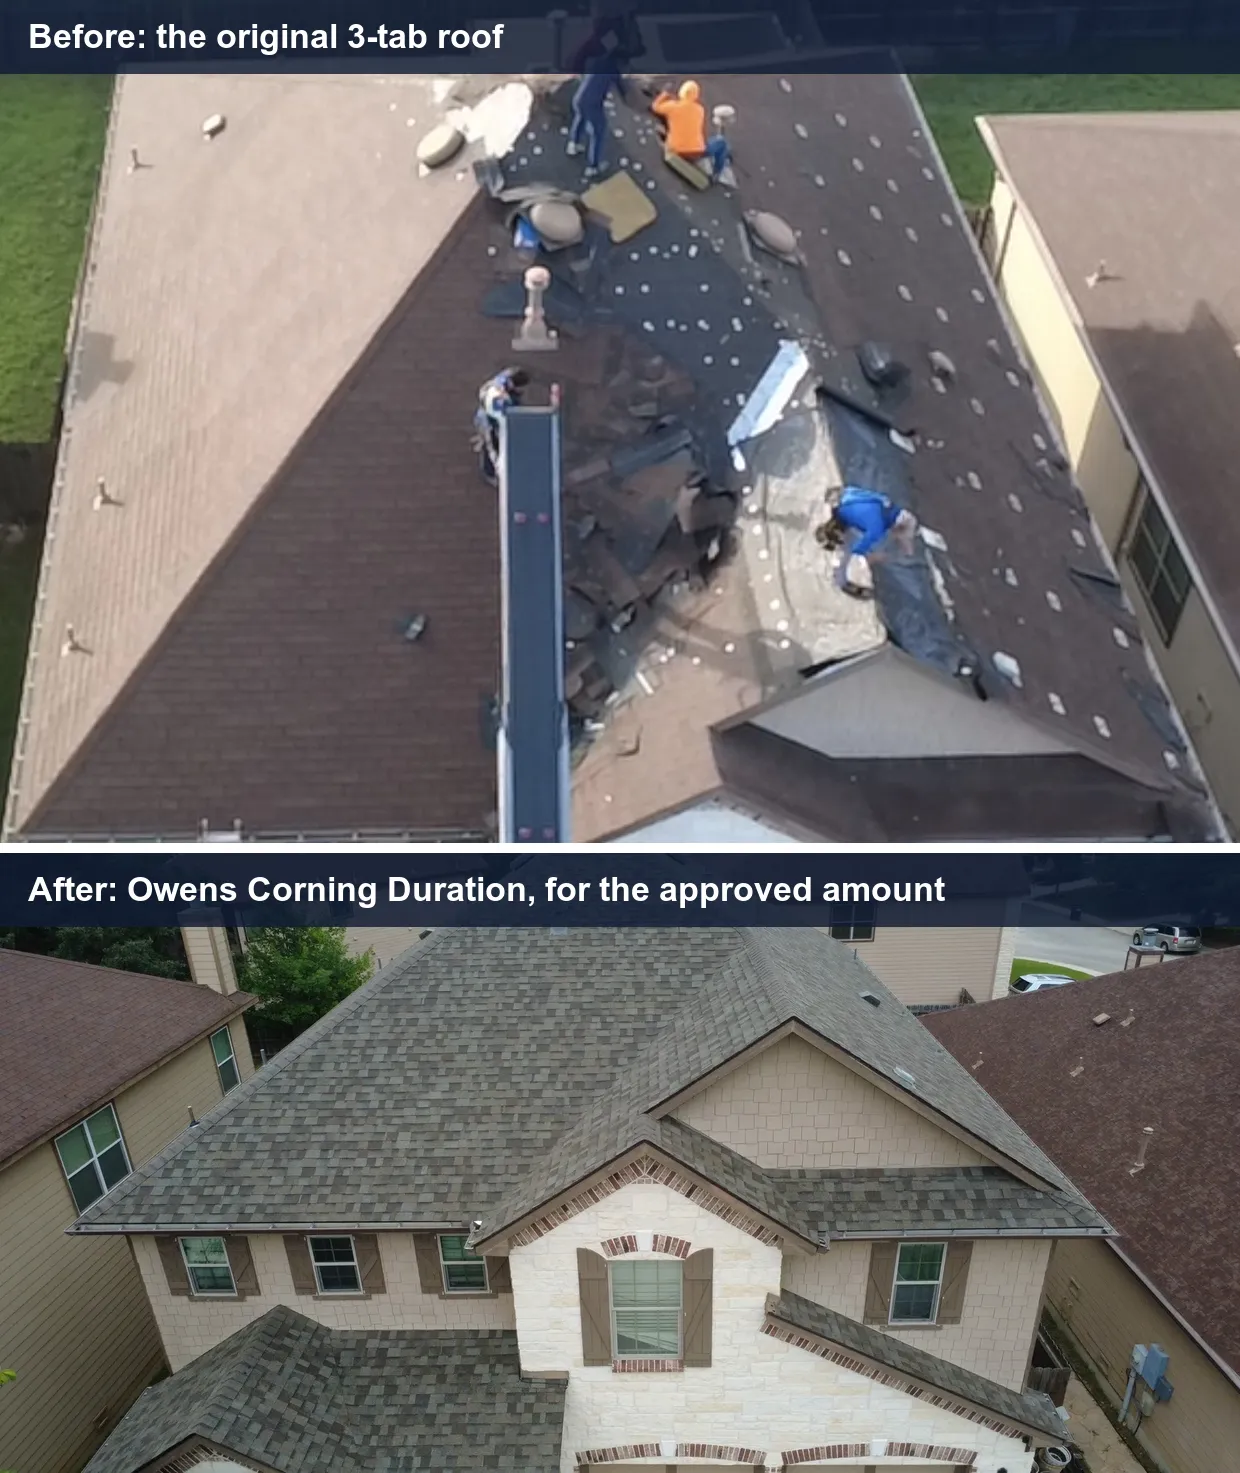
Roof Direct San Antonio works with insurance claims every storm season. Your adjuster's estimate pays to replace the roof you had, like for like. With us that same amount goes further.
Joshua H. lives on San Antonio's far West Side. Hail hit his roof in April 2025, and Allstate approved the claim at $14,040, written for 3-tab shingles. We installed Owens Corning Duration for that amount. He paid his deductible, insurance covered the rest, and the other roofers he called wanted about $5,000 more for the same upgrade.
- The upgrade. No sales commissions and no billboard budget in the price. On most claims a 3-tab roof comes back as Owens Corning Duration for the approved amount. A roof that already has architectural shingles can often step up to Duration STORM, a Class 4 impact-resistant shingle.
- What to send us. Your adjuster's worksheet or estimate and your claim number. Have your policy type (RCV or ACV) and the storm date handy for the call.
- Your deductible. You pay it to us. Financing is available through Synchrony.
- Start date. About a week from the day we have your estimate and claim number. Most roofs are finished in one day.
- Warranty. A 10-year workmanship warranty backed by Owens Corning through its Preferred Protection program, plus the limited lifetime shingle warranty.
Ready to start? Enter your address to see your price, then book the call and send us the estimate.
Does homeowners insurance cover roof replacement in Texas?
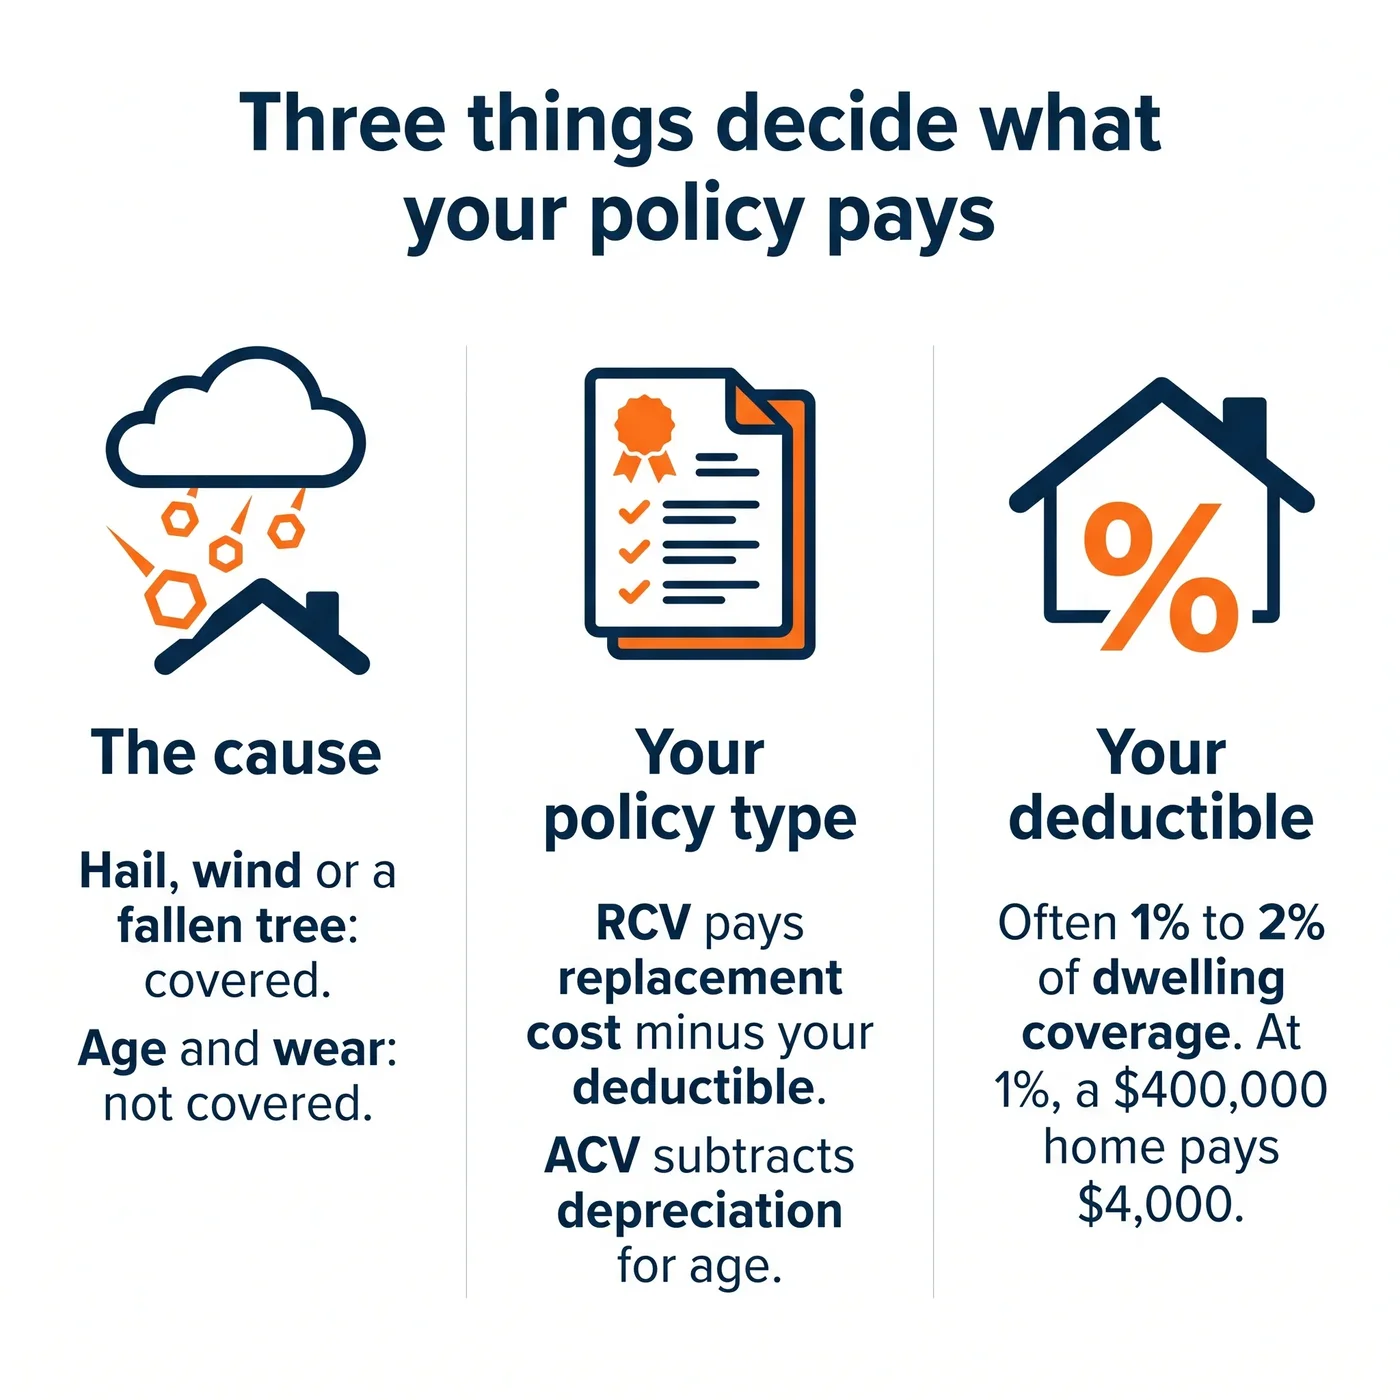
Yes. A standard Texas homeowners policy covers roof replacement when a covered event damages the roof: hail, wind, or a fallen tree. Three things decide what it pays.
- The cause. Storm damage is covered. Age and wear are not, which is why the storm date matters.
- Your policy type. RCV pays current replacement cost minus your deductible. ACV subtracts depreciation for the roof's age. Your declarations page says which you have.
- Your deductible. Wind and hail deductibles are often 1% to 2% of dwelling coverage. At 1%, a $400,000 home has a $4,000 deductible.
Roof insurance claim process in Texas: five steps
A hail damage roof insurance claim in Texas runs in five steps. Wind and storm claims follow the same path.
- Document the damage. Write down the storm date. Your insurer ties the claim to it, and your filing deadline counts from it. Photograph from the ground: dented gutters, downspouts, roof vents, window screens and AC fins, and the granules where the downspouts empty. Stay off the roof. We inspect it and write the report.
- File your claim. Check your deductible on the declarations page, then call your insurer or use its app. You get a claim number and a date for the adjuster visit. Your policy sets the deadline. Some Texas policies give one year from the date of damage, per the Texas Department of Insurance.
- Adjuster inspection. Your insurer sends an adjuster to assess the damage. We're on site for it and answer questions about the roof. You stay in control of your claim.
- Claim approval. If approved, your insurer pays based on your policy type, RCV or ACV. Most pay in two checks. The next section explains both.
- Roof replaced. Send us the adjuster's estimate and your claim number, and you pay your deductible.
Enter your address to see your replacement price before the adjuster visit, so you have a real number to set next to the estimate. Not sure the roof is damaged enough to file? See the signs on our hail damage roof replacement in San Antonio page.

ACV vs RCV and recoverable depreciation on a roof claim
Your policy type decides how much the insurer pays. It is on your declarations page, or your agent can tell you.
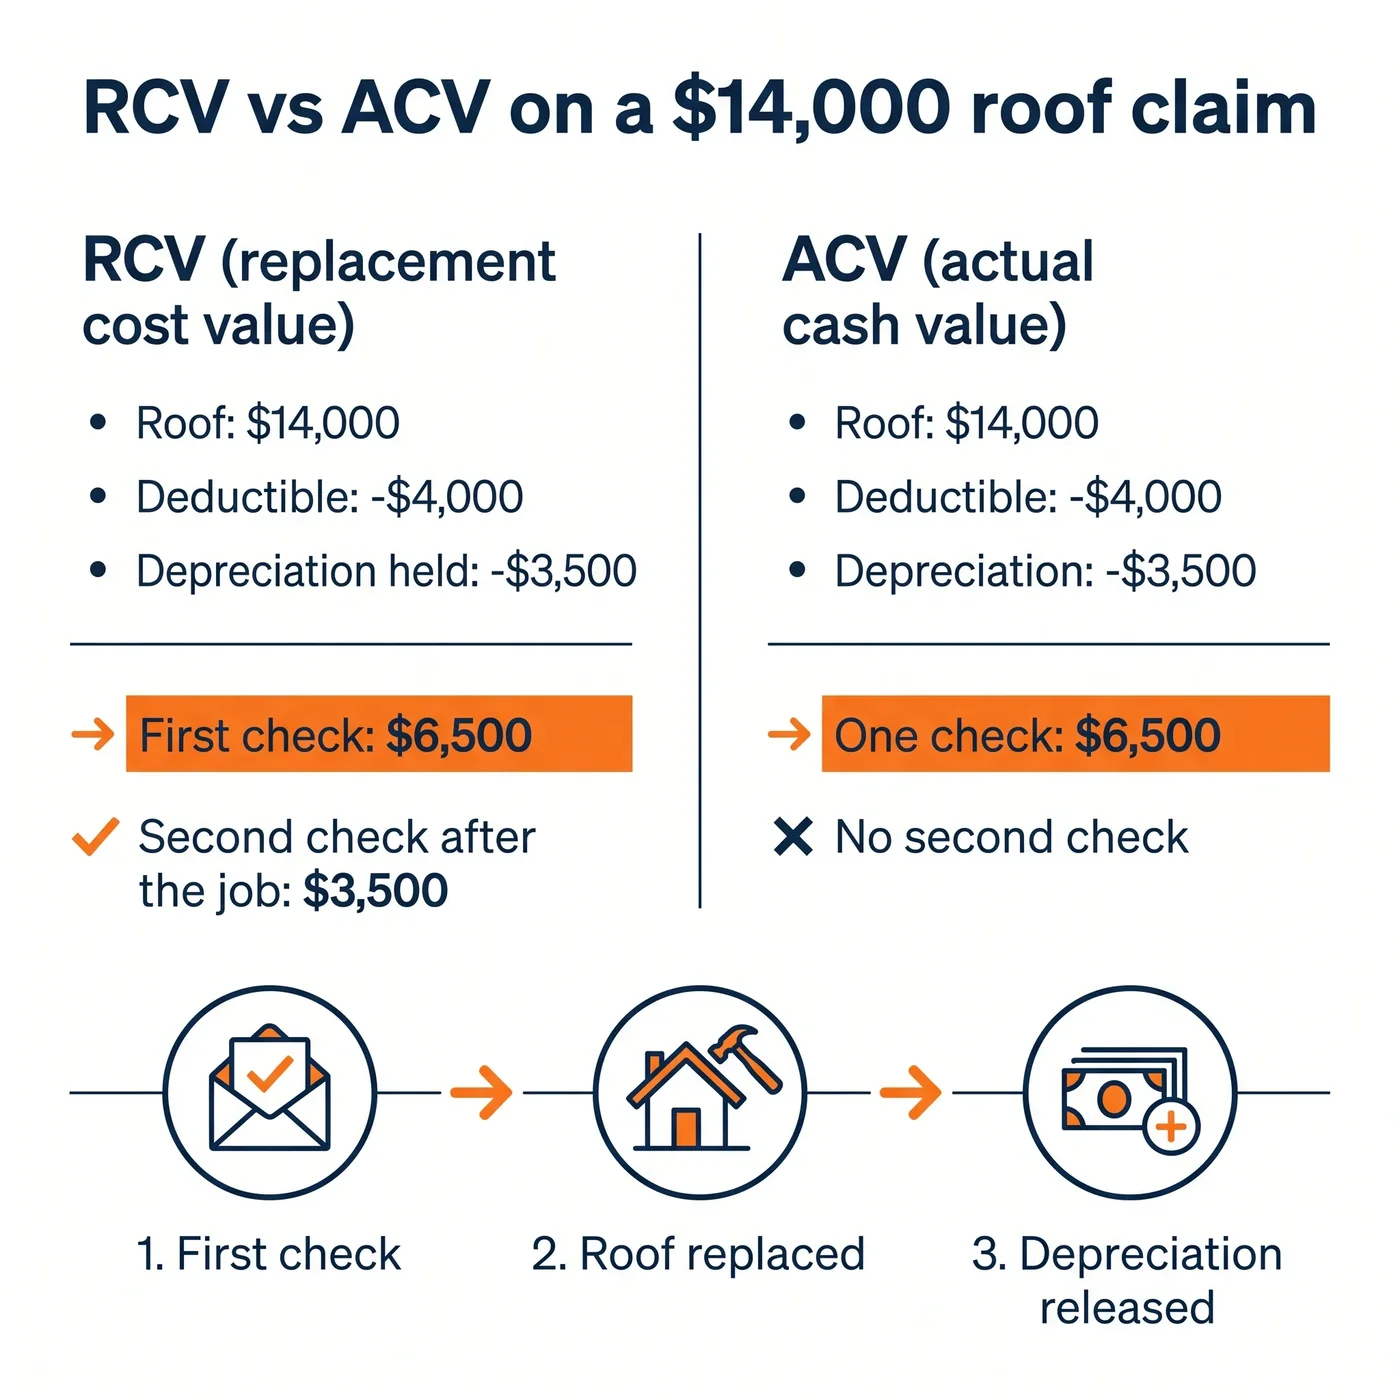
- RCV (replacement cost value): pays to replace the roof at current prices, minus your deductible.
- ACV (actual cash value): pays replacement cost minus depreciation. Depreciation is the value the roof has lost to wear and age.
- What ACV does to an older roof: the older the roof, the more depreciation comes off, so the payout shrinks with every year of age.
- Recoverable depreciation: on an RCV policy, most insurers pay in two checks. The first is the claim amount minus depreciation and your deductible. The second, the recoverable depreciation, comes after the insurer gets the bill for the finished job.
- Proof of deductible: insurers can hold the second check until you show the deductible was paid.
- Roofs over 10 to 15 years: many Texas insurers now move them to ACV or a roof payment schedule at renewal. Check before you file.
An example on a $14,000 roof with a $4,000 deductible and $3,500 of depreciation: RCV pays $6,500 up front and $3,500 after the job. ACV pays $6,500 and stops.
The definitions above follow the Texas Department of Insurance home insurance guide.
Enter your address to see your replacement price, then compare it to what your policy type would pay.
Questions about which policy type you have? Call us.
Call (210) 848-6538What San Antonio homeowners say
"Got three quotes for a roof replacement in San Antonio and Roof Direct came in almost $9,000 under the highest one and about $6,000 under the next. Same Owens Corning Duration shingles the bigger companies quoted, just no commissioned salesman markup baked in."

Joy Jasper
"We had storm damage and filed a claim thinking we'd just get the bare minimum roof to replace what was there. Daniel showed us how to use the insurance payout to actually upgrade our shingles and get a better warranty than what we had before. We ended up with a nicer roof than the one the storm destroyed and didn't pay anything extra out of pocket."
Sonda Lewis
Roof insurance claim denied: your four options in Texas
A denial is not always final. In Texas you have four options:
- Request a re-inspection. Ask your insurance company to send a different adjuster. Some damage is only visible from the roof itself.
- Get a written damage report. A report with photos from a licensed roofer gives your insurer evidence the first inspection may not have had. We provide these at no cost.
- File a complaint with TDI. The Texas Department of Insurance (800-252-3439) accepts consumer complaints about claim denials.
- Consider a public adjuster. A public adjuster works for you, not the insurance company, and charges a fee. They must hold a TDI license. We're roofers, not public adjusters, so we document the roof and you or your adjuster handle the claim.
Roofers who offer to waive your deductible
After major San Antonio storms, some roofers offer to "absorb" or "waive" the insurance deductible. In Texas that is a Class B misdemeanor for the roofer (Business and Commerce Code §27.02). Insurance Code §707.002 requires you to pay your own deductible.
Insurers can also hold the recoverable depreciation until you show the deductible was paid. You can report the offer to the Texas Department of Insurance fraud unit at 1-800-252-3439.
A roofer who waives your deductible has to make that money up somewhere, usually by padding the invoice to your insurer. Our price for roof replacement in San Antonio is public: enter your address and you see it before you talk to anyone. Your claim pays that price, minus the deductible you pay us. When the approved amount is more than our price, the difference goes into a better shingle, as the approved-claim section above explains.
If your deductible is close to our price, some homeowners skip the claim. Enter your address and decide with both numbers in front of you.
Frequently asked questions
Insurance paying for your roof? See your price first.
Your replacement price in under 2 minutes, no salesperson. The free inspection is scheduled on the call, whenever you want it.